

Western Union Send Money Now

- 151.80K Reviews
- 4.7
- Downloads
- 10,000,000+
Our take on Western Union Send Money Now from Appgk
Sending money across borders is one of those tasks that looks simple until the details matter: the recipient may need the funds quickly, the sender wants a clear total, and both people need confidence that the transfer is going to the right place. I tested Western Union Send Money Now with that practical situation in mind. It is a finance app from Western Union Apps, focused on international money transfers and remittances rather than everyday banking.
My overall impression is that it works best when you already know why you are sending money, who will receive it, and which delivery method suits them. The app gives the familiar Western Union service a more convenient mobile front end, while still making the transaction feel like something that deserves careful checking before confirmation. It is free to install, carries an Everyone age rating, and has built a substantial audience with over ten million installs and a 4.7 average from around 348 thousand ratings.
I would recommend it to someone who regularly supports family abroad, needs to arrange a transfer while away from a computer, or prefers handling the process from a phone. I would be more cautious about recommending it to somebody who expects a transfer app to behave exactly like a domestic bank payment. International remittances involve exchange rates, fees, recipient details, and local collection rules, so convenience does not remove the need to review the final transaction.
How the current mobile experience fits real money transfers
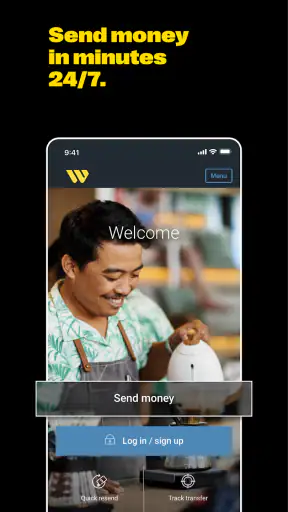
The first useful thing about this app is that it keeps the purpose narrow. You are not opening a full current account, tracking investments, or managing a broad collection of financial products. The focus is sending money internationally. That makes the experience easier to understand than a large banking app where remittances are buried among cards, bills, and account settings.
Best Parts of Western Union Send Money Now
Things to Keep in Mind About Western Union Send Money Now
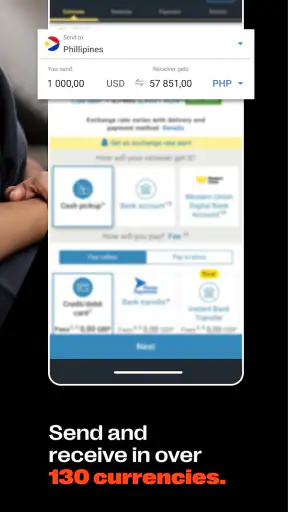
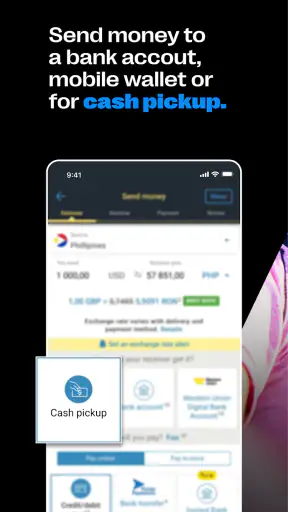
For a typical transfer, I would start by deciding how the recipient should get the money. Someone may need cash collection because they do not use a bank account, while another recipient may prefer funds delivered into an account. That choice affects the usefulness of the transfer more than the sender’s preferred interface. A good workflow is to ask the recipient first, then enter their details exactly as they provide them, including spelling and account information where relevant.
This is also where I found the app’s mobile format both helpful and demanding. A phone makes it possible to begin a transfer during a lunch break or while travelling, but a small screen makes it easier to overlook a digit or rush through a confirmation page. I strongly suggest treating the review screen as a checklist rather than a formality. Check the recipient’s name, destination, amount, currency, and the way the money will be made available before completing the send.
News and Features Related to Western Union Send Money Now

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The most important habit is to separate speed from certainty. A fast-looking workflow is valuable only when the recipient details are correct. If I were sending money to a family member for rent or an urgent household expense, I would confirm the recipient’s information in a separate message before opening the transfer screen. That small step is more useful than trying to correct a mistake after submission.
A realistic everyday scenario
Imagine that I am living in one country while a parent or sibling is handling an unexpected expense elsewhere. I can use the app to prepare the transfer from my phone, compare the amount the recipient should receive with the amount I am paying, and choose the delivery route that matches their circumstances. If they need cash, I would make sure they understand how and where they are expected to collect it. If they use an account, I would verify the account details character by character.
Don't want to read the full review?
That scenario shows why this is more than a simple “send” button. The sender and recipient have different needs. I care about the total leaving my side, while the recipient cares about the amount arriving and how accessible it will be. The app is most useful when both sides agree on those details before the transaction begins.
It is also worth remembering that the app does not turn international transfers into ordinary local payments. Exchange-rate movement and transfer charges can change the value of the transaction, and the recipient’s local process may affect when the money becomes usable. I would avoid promising a precise arrival time to someone who needs the funds for an appointment or bill until the app shows the relevant transfer information and I have checked the selected delivery option carefully.
Screenshots
Who will appreciate it most
The strongest audience is people who send remittances repeatedly and want a recognizable service available on their phone. If you support relatives in another country, the ability to start from a saved mobile workflow can be more practical than visiting a physical location every time. It is also useful for people who are comfortable checking financial details themselves and want to keep the process in one place.
It can suit occasional senders too, especially when the recipient does not have access to the same banking services as the sender. Western Union’s long-standing transfer identity may feel reassuring to someone who does not want to experiment with an unfamiliar peer-to-peer service for an important payment.
On the other hand, I would not choose it automatically for a transfer between two people who already use the same bank and can make a domestic payment easily. A bank transfer may be simpler in that situation. I would also hesitate if the main goal were holding multiple currencies, budgeting, or receiving a salary, because this app is designed around sending money rather than becoming a complete financial dashboard.
What the version history and maturity mean in practice
The app has been available since August 18, 2011, and the current version is 16.4. That combination tells me more than a launch announcement would: this is a mature mobile product, not a newly assembled transfer experiment. Its long presence gives it time to refine the mobile journey, while the current version shows that the application continues to be maintained.
For existing users, maturity is valuable because money-transfer apps benefit from predictable routines. Once I understand where to start a transfer, where to review the recipient, and where to check the final amount, I do not want every update to redesign the process without a clear reason. A mature release should make regular sending less intimidating, particularly for people who are not confident with financial apps.
The current version also creates a practical compatibility point. The app requires Android 8.0 or later, so most reasonably recent Android phones should be in the intended range, while an older device may need attention before installation. I would check the operating system before planning an urgent transfer. Discovering a compatibility problem when money needs to be sent immediately is exactly the kind of avoidable friction a little preparation prevents.
For someone already using an earlier release, I would approach an update in two stages. First, install the latest available version before an emergency rather than during one. Second, after updating, review the recipient workflow and account access before assuming everything feels identical. Even a small change in navigation can matter when you are working quickly, and financial transactions deserve a calm test run.
How the established service compares with common alternatives
The usual alternatives fall into several groups. A bank app may be better for transfers between accounts in the same banking network, particularly when both people value a familiar account history and domestic payments are straightforward. A digital wallet may be more convenient when both sender and recipient already use it, but that convenience depends on matching availability and an established account on both sides.
Western Union Send Money Now occupies a different position. Its appeal is not that every transfer is automatically the cheapest or simplest. Its appeal is the remittance-focused workflow and the possibility of serving recipients whose preferred way to receive money differs from the sender’s banking setup. That distinction matters when the recipient needs a practical collection route rather than another app account.
The trade-off is that a specialist remittance service still requires comparison. Before I confirm a transfer, I would look at the total cost and the amount the recipient is expected to receive, not just the headline amount I entered. For a large or recurring payment, even a small difference can matter over time. For a one-off urgent payment, the ability to use the recipient’s preferred delivery method may be worth more than chasing the lowest visible cost.
My advice is to compare alternatives based on the entire transaction, not the brand name. Ask four questions in your own mind: Can the recipient access the money in the needed way? Is the final received amount acceptable? Are the sender and recipient details easy to verify? Does the process fit the urgency? The app is a strong candidate when the answers line up, but another option may win when the transfer is local or both parties already share a convenient banking service.
Small workflow decisions that make a big difference
One useful technique is to prepare recipient information before starting. I would keep the recipient’s legal name and relevant account or collection details in a secure place, then copy them carefully rather than relying on memory. This is especially important when a relative uses a different spelling in everyday messages than in official financial records.
A second technique is to treat the first small transfer as a process check when circumstances allow. If I am sending to a new recipient and the payment is not urgent, a modest initial amount can help confirm that the delivery route and recipient information are correct before I send more. This is not necessary for every situation, but it is a sensible risk-reduction step for a new setup.
A third insight is to plan around the recipient’s access, not merely the sender’s convenience. A bank deposit may sound cleaner, but it is not helpful if the recipient cannot use that account easily. Cash collection may be more practical for one family member, while another may prefer an account. Choosing the route after speaking with the recipient avoids a common mistake: completing a technically successful transfer that is inconvenient to receive.
I would also keep a personal record of the transaction details after sending. That could mean noting the date, recipient, purpose, and confirmation information in a secure place. If I regularly support family, those notes make it easier to distinguish one transfer from another and to answer questions without guessing. The app can handle the transaction, but a simple personal record improves my own organization.
Where the experience still needs patience
The biggest limitation is not a missing button; it is the complexity surrounding international money. A clean mobile interface cannot remove exchange-rate questions, recipient verification, or local collection requirements. New users may expect the app to show one universally meaningful price, but the sender’s cost and the recipient’s received amount are the figures that deserve attention together.
There is also a human-error risk that becomes more serious on a phone. Small keyboards, autofill, rushed taps, and copied details can all create problems. I would avoid sending while distracted, especially if the recipient’s name resembles another contact or if I am switching between messaging and the transfer screen. The app’s convenience makes it easier to act quickly, but it does not make quick entry safer.
Another limitation is fit. People who want a complete banking relationship may find the experience too focused. Someone looking for spending analysis, savings goals, or a broad account overview should probably use a banking or personal-finance app designed for those tasks. Likewise, a person whose recipient can receive a simple local bank payment may gain little from choosing an international remittance tool.
I also would not judge the app solely by its high public rating. A 4.7 average across around 348 thousand ratings and roughly 152 thousand written reviews suggests broad satisfaction, while over ten million installs show that it has reached a large audience. Those figures are useful signals of adoption, but they cannot decide whether a particular transfer route, currency, or recipient situation is right for me. My own transaction details still matter more than the overall score.
Security-minded habits for senders
Because this is a finance app, I would be careful about where I install it and how I access it. The developer shown for the app is Western Union Apps, and I would make sure I am using the genuine store entry rather than a copied name or an unofficial download page. I would also avoid entering transfer information while connected to a network I do not trust, particularly if I am handling a large payment.
I would never ask a recipient to share more personal information than the transfer requires, and I would not send money simply because someone has created pressure or urgency. A familiar remittance brand cannot protect me from a social-engineering scam if I am sending to the wrong person. Before confirming, I would contact the recipient using a trusted channel and verify the purpose of the payment.
These habits are especially important for first-time users. The app can make the mechanics more accessible, but financial judgment remains the sender’s responsibility. If a request feels unusual, I would pause and confirm it outside the transfer conversation instead of allowing a countdown or emotional message to dictate the decision.
What I would watch as the app continues to evolve
The next useful improvements would be the ones that reduce uncertainty without making the process heavier. I would watch for clearer explanations around the total sender cost, the recipient’s expected amount, and the practical meaning of each delivery choice. Those details are more valuable to me than decorative changes because they directly affect whether I can make a confident decision.
I would also pay attention to how future releases handle continuity for existing users. With version 16.4 as the current release, the app has a responsibility to keep familiar tasks easy to find while improving clarity for newcomers. A good update should help a first-time sender understand the process without forcing a regular user to relearn every step.
Compatibility remains another sensible thing to monitor. Anyone relying on an older Android phone should keep the operating system requirement in mind before an urgent payment arises. I would rather check access in advance, sign in calmly, and review the transfer flow than discover a device problem when a family member is waiting.
Finally, I would judge future changes by whether they improve trust at the moment of confirmation. The best evolution for this kind of app is not simply more options; it is better guidance around the options already available. Clear recipient details, understandable totals, and a deliberate final review are the features that make a remittance app genuinely useful.
My recommendation after using it
Western Union Send Money Now is a sensible choice for international remittances when the recipient’s access matters as much as the sender’s convenience. I like its focused purpose, established presence, and mobile format. It is free to install and suitable for Everyone, while its Android 8.0 minimum keeps the technical requirement clear for people checking an older phone.
I would choose it for supporting relatives abroad, arranging a cross-border payment from a phone, or sending to someone who may need a delivery option beyond a standard domestic bank transfer. I would not choose it by default for local payments, full personal-finance management, or situations where a shared banking network already makes the transfer simpler.
My final advice is straightforward: decide how the recipient will access the funds, compare the total you pay with the amount they should receive, verify every personal detail, and leave enough time to resolve a problem before the money is urgently needed. Used with that discipline, Western Union Send Money Now is a practical remittance companion rather than just another finance download. It does not remove the decisions involved in sending money internationally, but it puts those decisions into a mobile workflow that I found approachable and useful.
Western Union Send Money Now FAQ
What is Western Union Send Money Now, and how does it work?
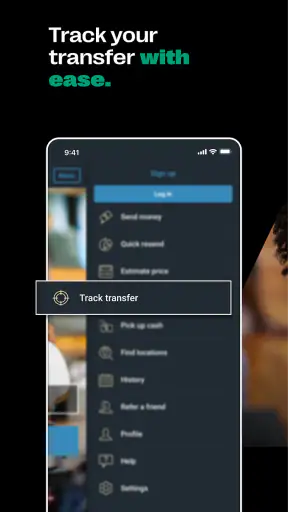
Western Union Send Money Now is a mobile service for sending money to people in other countries or locations. After creating an account, you enter the recipient’s details, choose a delivery method such as bank deposit, cash pickup, or mobile wallet where available, and pay for the transfer. The app then provides a tracking number so you can follow the transaction’s progress.
How much does it cost to send money with Western Union Send Money Now?
The total cost depends on several factors, including the amount being sent, destination country, payment method, delivery option, and exchange rate. The app normally displays the transfer fee and the estimated amount the recipient will receive before you confirm payment. Because prices can change, it is important to review the final quote carefully rather than relying on a general fee estimate.
How long does a Western Union money transfer take?
Transfer speed varies according to the destination, selected delivery method, payment option, operating hours, compliance checks, and local banking procedures. Some cash-pickup transfers may be available quickly, while bank deposits can take longer. The app provides an estimated delivery time during the transaction and allows you to track the transfer using its reference number.
What information or documents are required to send money?
You generally need to register with accurate personal information and provide the recipient’s full name and destination details. Depending on the transfer amount, country, payment method, or regulatory requirements, Western Union may request identity verification or additional documentation. The recipient may also need valid identification to collect cash, so names and details should match official documents exactly.
Is Western Union Send Money Now safe, and what should I check before confirming a transfer?
The service uses account security measures, transaction monitoring, and identity checks, but users should still take precautions. Only send money to people you know and trust, verify the recipient’s details, and never share passwords or verification codes. Be especially careful with requests involving prizes, emergencies, employment offers, or strangers, because completed transfers can be difficult to reverse.











